Smart Personal Finance: Simple Ways to Build a Stronger Financial Future
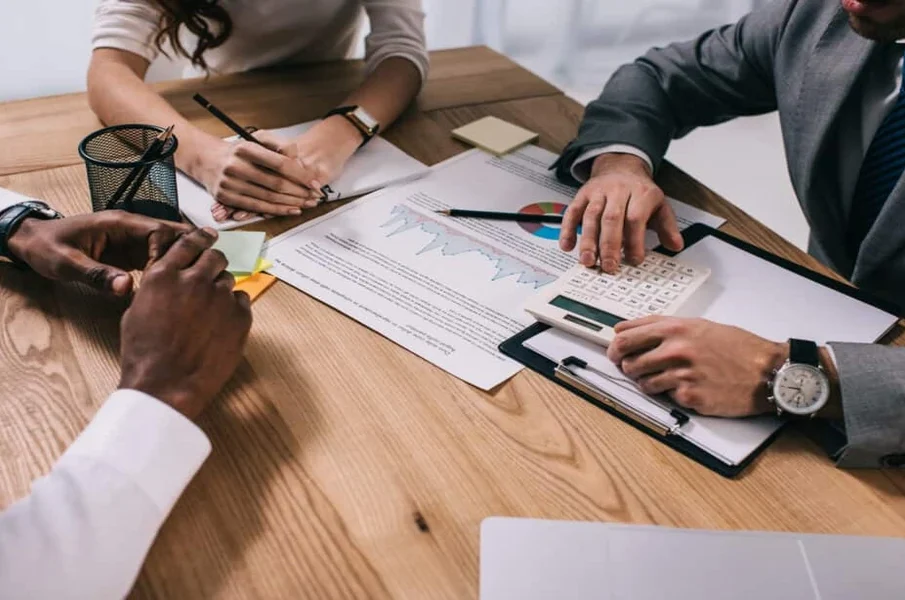
Managing personal finances does not always require complicated investment strategies or a high income. In many cases, financial stability starts with simple habits: knowing where your money goes, controlling unnecessary spending, saving regularly, and preparing for unexpected expenses.
A good financial plan should fit your actual lifestyle rather than forcing you to follow a perfect formula. Whether you are earning your first salary, working as a freelancer, or trying to manage household expenses, a few practical changes can make your money easier to manage.
Start With a Realistic Budget
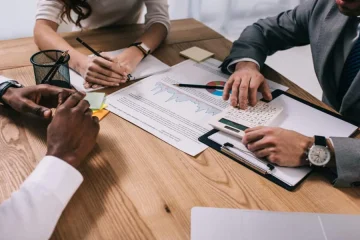
The first step toward better personal finance is understanding your monthly cash flow. Write down your take-home income and then list your regular expenses, including rent, groceries, transportation, utilities, subscriptions, debt payments, and entertainment.
A budget is not necessarily about cutting everything you enjoy. Instead, it gives you a clear picture of where your money is going. The Consumer Financial Protection Bureau recommends tracking expenses and comparing your spending with your monthly income so that your budget reflects your actual financial situation.
You may also discover small expenses that seem insignificant individually but become substantial over several months.
Build an Emergency Fund
Unexpected expenses are one of the biggest challenges in personal finance. A car repair, medical bill, home repair, or temporary loss of income can quickly disrupt an otherwise balanced budget.
An emergency fund is money kept specifically for these unplanned situations. The CFPB notes that even small amounts can provide some financial protection and help people avoid relying entirely on credit or loans when an unexpected expense occurs. (Consumer Financial Protection Bureau)
If saving several months of expenses feels impossible, start with a smaller target. For example, you could initially aim for $500 or $1,000 and gradually increase the amount as your financial situation improves.
The important part is creating the habit rather than waiting until you can save a large amount.
Make Saving Automatic
Saving becomes easier when you do not have to make the decision every month. Consider setting up an automatic transfer from your checking account to a dedicated savings account after receiving your income.
Even a modest automatic contribution can add up over time. CNBC Select has also highlighted automation as a practical way to make saving more consistent without requiring constant attention. (CNBC)
You can divide your savings into different goals, such as emergency expenses, travel, a future purchase, or long-term financial goals. Keeping these goals separate can make your progress easier to see.
Be Careful With High-Interest Debt
Debt can be useful in certain situations, but high-interest debt can make it difficult to build wealth. Credit card balances, in particular, can become expensive when only minimum payments are made.
Before taking on new debt, consider whether the purchase is necessary and whether the monthly payment comfortably fits into your budget. If you already have debt, review your balances, interest rates, and minimum payments. You can then create a repayment strategy based on your income and priorities.
At the same time, avoid completely ignoring emergency savings while paying debt. Having at least some cash available can help prevent a small financial emergency from turning into additional borrowing.
Learn From Your Financial Experiences
Personal finance is not only about numbers. Your financial decisions are influenced by your habits, priorities, family situation, and past experiences.
If you have made financial mistakes before, use them as information rather than allowing them to discourage you. You can also learn from other people’s experiences. For example, personal finance stories can provide useful perspectives on how people approach budgeting, saving, borrowing, and financial challenges. Share Your Financial Story on WithULoan
For additional personal-finance guidance, resources from the Consumer Financial Protection Bureau can also help you understand budgeting and saving strategies.
Create a Financial Routine
Good money management does not need to take hours every week. Set aside 20-30 minutes once a week or once a month to review your bank accounts, upcoming bills, savings progress, and spending.
Small adjustments can make a meaningful difference over time. You might cancel an unused subscription, reduce an unnecessary expense, increase an automatic savings transfer, or simply become more aware of your spending.
Ultimately, personal finance is about building a system that works for you. A realistic budget, consistent saving, responsible borrowing, and regular financial checkups can help create a stronger foundation for the future. You do not need to change everything at once. Start with one manageable habit, stick with it, and gradually build from there.


-
Smart Personal Finance: Simple Ways to Build a Stronger Financial Future
Managing personal finances does not always require complicated investment strategies or a ... -
-
-
-